Mortgage calculator: payment, interest and schedule – before you visit the bank
An apartment is the biggest purchase most people ever make – and paying for it takes 10 to 30 years. We have launched a mortgage calculator: it computes your real monthly payment and total interest and shows how the schedule changes with early repayments – before you visit the bank and sign anything.
Why it matters
Banks calculate in different ways: the down payment in money or in percent, a “from” rate without insurance, and the schedule only after you apply. The calculator boils it all down to clear numbers: payment, interest and total paid over the term – for the terms actually offered to you. Compare two offers: a difference of just half a percentage point – 7% versus 7.5% on an $800,000 mortgage over 30 years – means roughly $100,000 in extra interest.
How to use it
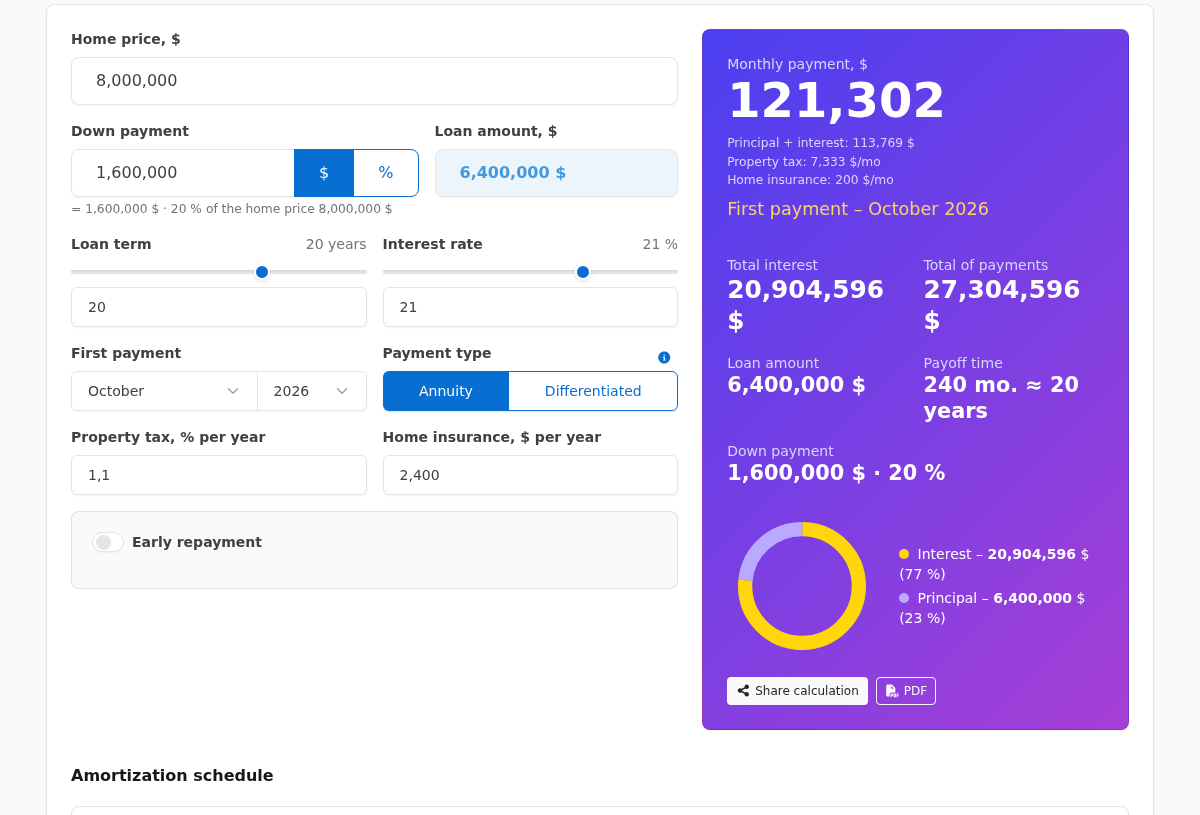
Enter the home price, the down payment – in money or in percent (the switch is next to the field) – the term and the rate from the bank offer. Choose the payment type: annuity (the same payment for the whole term) or differentiated (the payment decreases, the interest is lower). Everything recalculates instantly – just move the sliders.
Early repayments
Almost every mortgage gets early repayments sooner or later: a bonus, savings. Turn on the “Early repayment” switch and add one or several repayments – each with its month and amount. Each repayment has its own recalculation method: reduce the payment (easier every month) or reduce the term (cheaper in interest). The table shows how many months shorter the mortgage becomes, and the chart shows the balance dropping.
What the calculator shows
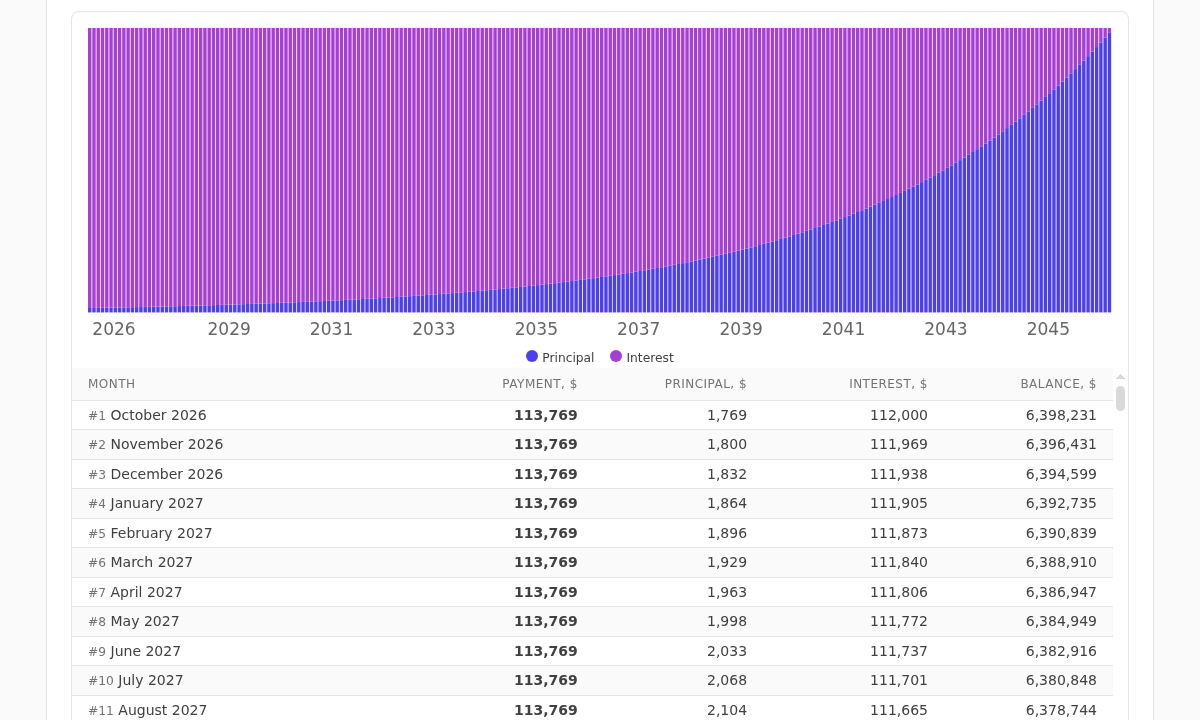
The results panel gives the essentials: monthly payment, interest and total paid. Below is a month-by-month schedule with a repayment chart: you can see how in the first years almost the whole payment goes to interest, and towards the end – to the principal. Hover a bar for the month figures, click to scroll to the schedule row. You can share the calculation by link (the recipient sees it in the same currency) or print it to PDF – with parameters, totals and the schedule.
For homebuyers
A practical habit: before applying, calculate the payment at a rate 1–2 points above the advertised one – if your budget survives it, no rejection or pricier approval can surprise you. Compare the annuity and differentiated schedules: the second is noticeably cheaper in interest but demands a higher payment in the first years. If the goal of early repayments is a financial cushion, choose a lower payment, not a shorter term.
For realtors and mortgage brokers
The calculator doubles as a work tool. In a client meeting, you can enter the price of a specific home and the available down payment right on the screen – nothing is stored or sent anywhere – show the payment and interest for offers from several banks and answer “what if we pay it down early?” with numbers. The PDF button turns the calculation into a neat document the client takes home.
Try the calculator: link above. The calculation is preliminary – exact terms are set by the bank.